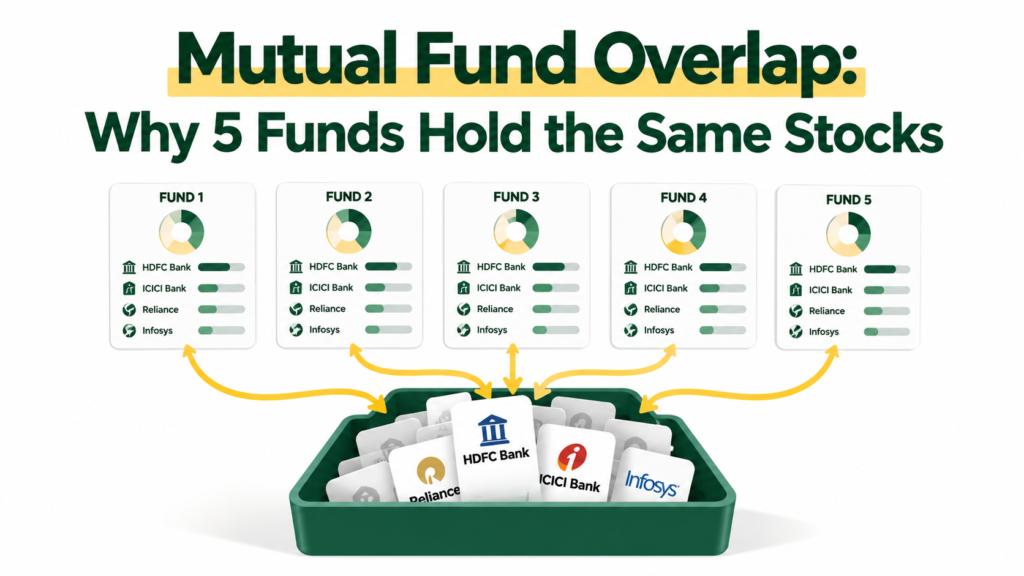
Many investors own five or six equity funds from different fund houses and believe they are well diversified. When the same banks and large companies sit in the top holdings of every fund, they are not. This is called mutual fund overlap. This article explains how it works, shows overlap data from Indian funds, and gives a step-by-step method to check and fix your own portfolio.
|
Quick answer • Overlap means different funds hold the same stocks. It is measured by portfolio weight, not only by the number of common stocks. • It is common in India because large-cap, flexi-cap and index funds all pick from the same group of top companies. • Five overlapping funds cost you five expense ratios while giving the exposure of one or two. • Overlap is not always wrong. It is a problem when you did not choose it on purpose. • Check it with fund portfolios and an overlap calculator, then merge funds that do the same job. |
What is mutual fund overlap?
Mutual fund overlap is the part of your portfolio that is duplicated across funds. If Fund A and Fund B both hold HDFC Bank and ICICI Bank, you own those two stocks twice, even though you paid two fund houses.
The standard method works by weight. For every stock both funds hold, take the smaller of the two weights and add them up (Sharpely overlap calculator). If Fund A holds HDFC Bank at 8% and Fund B at 6%, the overlap on that stock is 6%. If the total across all shared stocks is 40%, then 40% of the combined portfolio weight is duplicated. Counting shared stocks alone can mislead, because two funds may share 20 stocks that carry small weights.
Why Indian equity funds overlap so much
Category rules push funds to the same pool. SEBI’s categorisation requires a large-cap fund to hold at least 80% in large-cap companies, defined as the top 100 by market capitalisation (AMFI; Kotak Mutual Fund). Active large-cap managers therefore choose from the same universe that Nifty 50 and Nifty 100 index funds track (Retirewise).
A few stocks dominate the index. As of 31 August 2026, the Nifty 50 weights were HDFC Bank 9.85%, ICICI Bank 9.45% and Reliance Industries 7.83%. The five banks in the top ten together made up about ₹29.47 of every ₹100, and Financial Services was 36.47% of the index (INDmoney).
The same private banks sit in most portfolios. In a July 2026 comparison of five large flexi-cap funds, HDFC Bank appeared in all five and ICICI Bank was a top-three holding in four (INDmoney).
Five funds, same stocks: a real example
The table shows two stocks across five flexi-cap funds, as on 30 June 2026. These funds are examples from public data, not recommendations.
|
Fund |
HDFC Bank weight |
ICICI Bank weight |
|
Franklin India Flexi Cap |
7.83% |
6.34% |
|
HDFC Flexi Cap |
6.77% |
9.18% |
|
PGIM India Flexi Cap |
6.10% |
5.98% |
|
Parag Parikh Flexi Cap |
8.33% |
5.52% |
|
Aditya Birla Sun Life Flexi Cap |
3.58% |
6.10% |
|
Simple average |
6.5% |
6.6% |
Source: fund comparison pages on Sharpely (Franklin vs Parag Parikh; Franklin vs PGIM; Aditya Birla vs HDFC; HDFC vs PGIM).
Suppose you put ₹2 lakh in each of these five funds, ₹10 lakh in total. You would hold about ₹65,000 in HDFC Bank and ₹66,000 in ICICI Bank, roughly 13% of the portfolio in two stocks. That is similar to owning just one of these funds. You still pay five expense ratios, which range from 0.74% to 0.99% for the direct plans of four of these funds.
Pairs of funds in the same category can also differ a lot. Overlap by weight for some popular pairs, as on 30 June 2026:
|
Pair of flexi-cap funds |
Overlap by weight |
Reading |
|
48.4% |
Moderate to high |
|
|
39.7% |
Moderate |
|
|
38.2% |
Moderate |
|
|
35.9% |
Moderate |
|
|
32.4% |
Moderate |
|
|
13.2% |
Low |
Holdings change every month, so treat these as a snapshot. The range from 13% to 48% shows that two funds with the same label can be near twins or genuinely different. The name of the category does not tell you which.
Why overlap hurts your portfolio
• Concentration risk. When the shared stocks fall, every fund falls together. On 20 July 2026, for example, the Nifty 50 slipped below 24,200 with banking stocks leading the decline (Angel One). A portfolio heavy in the same banks feels that move in all its funds at once.
• Higher cost for similar exposure. Each fund charges its own expense ratio, so duplicated holdings mean duplicated fees.
• False comfort. Five fund names on a statement look diversified. The holdings underneath tell a different story.
• Harder to manage. With many similar funds it is difficult to see what drives returns or what to rebalance.
Our note on how market corrections affect investors shows why knowing what you actually own matters before a fall, not after it.
When overlap is acceptable
• You hold an index fund as the core and want the same large companies on purpose.
• The shared stocks carry small weights in both funds.
• The funds sit in different categories. A flexi-cap and a small-cap fund will share little. Sharpely’s data shows two large small-cap funds with 70 common stocks but low combined weight, so they still complement each other (Sharpely).
Large-cap funds are the exception. Two of them will almost always overlap heavily, so a second large-cap fund rarely adds diversification.
How to check overlap in five steps
1. List every equity fund you own, including SIPs, ELSS and index funds. A consolidated account statement from CAMS or KFintech shows all of them.
2. Open each fund’s latest monthly portfolio or factsheet on the fund house website and note the top 10 holdings.
3. Run each pair through an overlap calculator such as Sharpely’s.
4. Read the list of common holdings, not just the percentage. As a rule of thumb, treat 40% or more between two funds of the same category as a flag.
5. Compare categories and styles. Funds with the same job are the ones to merge.
How to fix overlap
• Give each fund one job. For example, a large-cap or index core, one flexi-cap, one mid-cap, one small-cap, plus debt, gold or international funds based on your asset allocation.
• Keep one fund per job. If two funds do the same job, keep the one with the better process, cost and consistency.
• Stop new SIPs in the duplicate first. This has no tax cost. Redirect that amount to the fund you keep.
• Exit old units in stages. Selling equity units triggers tax: 20% on gains held 12 months or less, and 12.5% above ₹1.25 lakh of long-term gains in a year (Outlook Money). Our tax harvesting guide explains how to use the annual exemption, and the lump sum vs STP guide shows how to move a large amount in parts.
• Review every 6 to 12 months. Many advisers suggest roughly 4 to 6 funds for most investors (Finnovate), though the right number depends on your goals.
Frequently asked questions
What is overlap in mutual funds?
It is the share of a portfolio duplicated across two or more funds because they hold the same stocks. It is best measured by portfolio weight.
What is a high overlap percentage?
There is no official limit. Among funds of the same category, 40% or more suggests they are close to duplicates. Sharpely labels overlaps of roughly 30% to 50% as moderate, so read the common holdings as well.
Can an index fund and an active fund overlap?
Yes. Active large-cap funds pick from the same top 100 companies that Nifty 50 and Nifty 100 index funds track, so overlap is common.
Is overlap always bad?
No. It is acceptable when it is deliberate, such as an index core with a similar large-cap holding, or when the shared stocks have small weights.
How many mutual funds should I own?
There is no fixed number. Many advisers suggest around 4 to 7 funds across different categories, with each fund serving a distinct purpose.
Should I sell overlapping funds immediately?
Not necessarily. Stop fresh SIPs in the duplicate first, then check tax and exit load before selling units. Doing it in stages can reduce the tax.
How often should I check overlap?
Every 6 to 12 months, and when you add a new fund. Fund holdings change each month.
How SJS Finserve can help
Most investors discover overlap only when they compare holdings fund by fund. At SJS Finserve, a portfolio review covers:
• Which of your funds hold the same stocks, and by how much.
• Which funds to keep, merge or stop, based on your goals and risk level.
• How to switch in stages with the tax impact in mind.
You can try our calculators, and contact us for a free consultation.


