A balanced advantage fund (BAF), also called a dynamic asset allocation fund, is a hybrid mutual fund that invests in equity and debt and changes the mix on its own as market conditions change. When the stock market looks expensive, the fund reduces equity. When it looks cheaper, the fund increases equity. You do not need to place any switch or rebalancing order yourself.
This is the main reason BAFs are worth understanding. Most investors find it hard to cut equity when markets rise and add equity when markets fall. A BAF follows a rule for this inside the fund.
This article explains how a BAF works, what AMFI data shows about its behaviour in falling and rising markets, how it is taxed in FY 2026-27, and who should invest.
Key Takeaways
• A BAF can hold anywhere from 0% to 100% equity. SEBI does not fix a range for the category.
• The fund shifts between equity and debt using a model, and rebalances inside the scheme without creating a tax event for you.
• Category data since 2019 shows BAFs fell less than equity funds in most falling months, and gained less in rebounds.
• Models differ widely between funds, so the scheme you choose matters more than the category.
What Is a Balanced Advantage Fund?
A balanced advantage fund is a hybrid scheme that invests in equity, debt and, in many cases, arbitrage positions. SEBI defines the category as equity and debt investment that is managed dynamically, with 0% to 100% allowed in either asset class (category definitions). In practice, most BAFs work within a narrower band, commonly described as roughly 30% to 80% equity (Tata Capital), but the rules do not force this.
The table below shows how BAFs differ from other hybrid categories.
|
Hybrid category |
SEBI allocation rule |
Who decides the mix |
|
Balanced hybrid |
40% to 60% equity, 40% to 60% debt |
Fixed range, the fund stays inside it |
|
Aggressive hybrid |
65% to 80% equity, 20% to 35% debt |
Fixed range, the fund stays inside it |
|
Balanced advantage (dynamic asset allocation) |
0% to 100% in equity or debt |
The fund’s model or manager, changing with the market |
|
Multi asset allocation |
At least 3 asset classes, minimum 10% in each |
The fund, above the 10% floors |
Table 1: SEBI hybrid fund categories. Source: SEBI category definitions as summarised by Arthgyaan.
Why Balanced Advantage Funds Are Interesting
Two features set BAFs apart from most other mutual funds: automatic asset allocation based on market conditions, and automatic rebalancing of your portfolio.
Feature 1: Automatic Asset Allocation Based on Market Conditions
Every BAF follows a model that decides how much to hold in equity. The inputs differ by fund house, but they fall into three types (freefincal analysis of fund models):
• Valuation-based models compare a market measure, such as the Nifty price-to-earnings (P/E) ratio, with its own history. The higher the valuation, the lower the equity.
• Trend-based models use price signals such as moving averages to raise or lower equity.
• Discretionary models leave the decision to the fund manager, who weighs valuations, interest rates and earnings outlook.
Illustration (hypothetical numbers): a fund’s model holds 70% equity when the Nifty P/E is low, 50% when moderate and 30% when high. If markets rise and the P/E moves from moderate to high, the fund moves from 50% to 30% equity and holds the rest in debt. If markets later fall and valuations become low, it moves back towards 70%.
Investor behaviour often works the other way. After the COVID fall, BAFs saw net outflows in every month from March to December 2020, about ₹5,699 crore in total (INDmoney analysis of AMFI data). The fund is designed to do the opposite: hold less equity as markets get expensive and more as they get cheaper.
Feature 2: Automatic Rebalancing of Your Portfolio
Rebalancing means bringing a portfolio back to its intended mix of equity and debt. If you hold an equity fund and a debt fund separately, you must track the ratio, redeem units of one and buy the other. Each redemption is a taxable event: in FY 2026-27, equity fund gains within 12 months are taxed at 20%, and gains after 12 months at 12.5% above ₹1.25 lakh a year (Budget 2026 tax summary). Exit loads may also apply.
In a BAF, the shifting happens inside the scheme and your number of units does not change. You pay capital gains tax only when you redeem your own units, not each time the fund changes its mix. This removes both the effort and the repeated tax cost of rebalancing by hand. For redemption planning, see our guide on tax harvesting in mutual funds.
Gross Equity, Net Equity and Arbitrage
Many BAFs hedge part of their shares by selling futures. Hedged shares count in gross equity but add little market risk, so net equity is the figure that shows real exposure to a fall (INDmoney). The hedged portion, called arbitrage, also helps a fund stay at or above 65% equity for tax purposes (Bajaj Finserv AMC). Check both numbers on the factsheet.
How Balanced Advantage Funds Behaved in Indian Market Falls
AMFI publishes category assets and flows every month. INDmoney used this series from April 2019 to August 2026, removing net investor flows from each month’s change in assets, to estimate how each category moved (full analysis). These are category estimates, not fund NAV returns, but they show the pattern.
|
Falling period |
Equity schemes (estimated move) |
Balanced advantage funds (estimated move) |
|
July to August 2019 |
-7.8% |
-6.2% |
|
February to March 2020 |
-29.2% |
-21.4% |
|
November 2021 to June 2022 |
-11.5% |
-3.2% |
|
October 2024 to February 2025 |
-17.4% |
-8.3% |
|
March 2026 |
-10.8% |
-7.5% |
Table 2: AUM-implied category moves during market falls. Source: INDmoney, based on AMFI monthly data.
Across the 86 months in the series, equity schemes had a negative move in 27 months. In 24 of those 27 months, BAFs moved less negatively than equity schemes. In those falling months, the average equity-scheme move was about -3.9%, compared with about -2.4% for BAFs.
What You Give Up When Markets Rebound
A fund carrying less equity captures less of a recovery. In five sharp rebound months, BAFs gained between 50% and 72% as much as equity schemes. Across the full period, BAF moves were about 61% as large as equity-scheme moves in down months and 59% in up months. Note that BAFs still fell an estimated 21.4% in February and March 2020, so a smaller fall is still a fall.
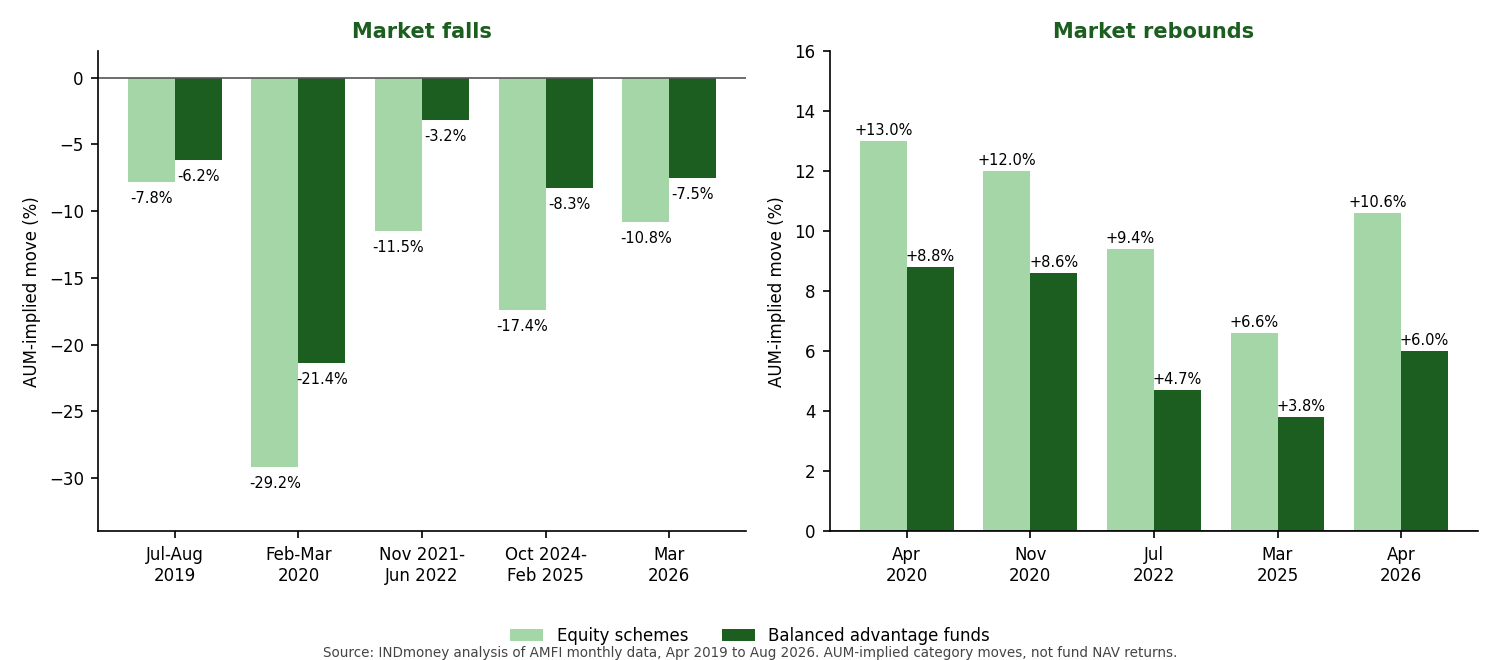
Figure 1: Estimated category moves of equity schemes and BAFs in falls and rebounds. Source: INDmoney, based on AMFI monthly data.
If a smaller decline helps you stay invested through a fall, lower participation in the rebound may be acceptable. If you can already tolerate full equity swings, a BAF may feel restrictive in a recovery.
The Scheme You Choose Matters
In the February to March 2020 fall, schemes in this category lost between about 12.7% and 33.2% (freefincal). Some funds do little hedging and behave like aggressive hybrid funds, while others keep low net equity (PrimeInvestor). Two funds with the same label can give very different results.
Balanced Advantage Fund Data for India (2026)
|
Metric |
Figure |
Period |
|
BAF category assets under management |
₹3.16 lakh crore |
September 2026 |
|
Share of total mutual fund industry assets |
3.82% |
September 2026 |
|
Number of folios (accounts) |
57.74 lakh |
September 2026 |
|
Net flow into BAFs |
Outflow of ₹912.43 crore |
September 2026 |
|
BAF assets, April 2019 to August 2026 |
₹92,833 crore to ₹3,29,104 crore |
2019 to 2026 |
|
Total mutual fund industry assets |
₹82.64 lakh crore |
30 September 2026 |
|
Monthly SIP contributions, whole industry |
₹32,490 crore (record) |
September 2026 |
Table 3: BAF category data. Sources: Tapetide (AMFI category report), 5paisa, Zee Business and INDmoney.
BAF folios have risen from 24.6 lakh to 57.7 lakh since 2019, yet BAF assets as a share of equity-scheme assets fell from 13.2% to 8.4% (INDmoney).
In September 2026, while markets fell and industry SIP contributions hit a record, BAFs saw net outflows of ₹912.43 crore. Flows have often weakened during or after falls, exactly when a smoother ride is meant to help investors stay invested. For the current backdrop, see our notes on Nifty at a 52-week low and why volatility helps investors in a correction.
Taxation of Balanced Advantage Funds in FY 2026-27
BAFs are taxed by how much domestic equity they hold, including arbitrage positions, not by their name.
|
Equity holding |
Short-term gains |
Long-term gains |
|
65% or more (equity-oriented) |
20% if sold within 12 months |
12.5% on gains above ₹1.25 lakh a year, after 12 months |
|
35% to 65% |
Taxed at your income tax slab rate if sold within 24 months |
12.5% with no ₹1.25 lakh exemption, after 24 months |
Table 4: Capital gains tax on hybrid funds, FY 2026-27. Sources: Income Tax on Mutual Fund Returns 2026 and JM Financial.
Budget 2026 left these rates unchanged (Sahi). Many BAFs use arbitrage to stay above 65%, but this depends on each scheme’s holdings. Check the latest scheme documents and confirm your position with a tax professional.
Risks and Limits of Balanced Advantage Funds
• They can lose money. A BAF is not a fixed deposit and does not protect your capital.
• They lag in rallies. BAFs have captured roughly 59% of equity-scheme moves in up months.
• Models can be wrong. A model may cut equity early in a long rally, or add equity in a market that keeps falling.
• Costs apply. Compare the expense ratio and exit load with the role the fund plays in your portfolio.
Who Should Consider a Balanced Advantage Fund
A BAF may suit:
• First-time equity investors who worry about full equity volatility.
• Investors with a lump sum who are concerned about entering at a high market level. See our guide on lump sum vs STP.
• Investors with goals three to five years or more away who prefer a smoother path than a pure equity fund.
A BAF may not suit:
• Emergency money or goals that are one to two years away.
• Investors with 10 years or more who can tolerate full equity swings and want maximum participation in gains.
• Anyone expecting guaranteed or fixed-deposit-like returns.
To size your monthly investment for a goal, see how much SIP you need for ₹1 crore and our goal-based investing guide.
How to Choose a Balanced Advantage Fund
1. Model type. Check whether the fund uses valuations, trends or manager discretion, and how much room it has to change equity.
2. Net equity range. Check the lowest and highest net equity over the last three to five years, not only today’s figure.
3. Past falls and recoveries. Compare NAV behaviour in 2020, 2022 and 2024-25 against the category.
4. Tax status. Confirm the fund consistently holds 65% or more in equity including arbitrage.
5. Cost and debt quality. Compare expense ratios and exit load, and check the credit quality of the debt portion.
6. Fit with your goal. Decide what share of your total portfolio should sit in a BAF.
How SJS Finserve Can Help
SJS Finserve Private Limited is an AMFI-registered mutual fund distributor (ARN 332811) based in Gurugram, working with families and investors across Delhi NCR. Choosing a BAF is not a one-time decision. It needs a scheme comparison, a view on how much of your portfolio it should occupy, and regular reviews as markets and goals change.
Our wealth advisory process has four steps: understand your income, family and goals; design a plan that shows how much each goal needs and whether a BAF fits; implement it through SIP, lump sum or STP; and review it regularly. You can test your own numbers with our investment calculators, and learn more about our team and our firm.
If you want to know whether a balanced advantage fund fits your goals, or want help building and reviewing your mutual fund portfolio, contact SJS Finserve for a free consultation.
Frequently Asked Questions
What is a balanced advantage fund?
A balanced advantage fund is a hybrid mutual fund that invests in equity and debt and changes the mix automatically as market conditions change. It is also called a dynamic asset allocation fund, and SEBI allows 0% to 100% in either asset class.
How does a balanced advantage fund decide how much to invest in equity?
Each fund uses its own model. Valuation-based models cut equity when markets look expensive and add it when they look cheaper. Trend-based models use price signals, and discretionary funds rely on the manager’s judgement.
Is a balanced advantage fund safe?
It is not risk-free and does not guarantee returns. BAFs fell an estimated 21.4% in February and March 2020. They have generally fallen less than equity funds, but they can still lose money, especially over short periods.
How are balanced advantage funds taxed in FY 2026-27?
If the fund holds 65% or more in equity including arbitrage, short-term gains (up to 12 months) are taxed at 20% and long-term gains at 12.5% above ₹1.25 lakh a year. Funds below 65% equity are taxed differently, so check the scheme’s actual holdings.
What is the difference between a balanced advantage fund and an aggressive hybrid fund?
An aggressive hybrid fund must keep 65% to 80% in equity at all times. A balanced advantage fund has no fixed range and can cut equity when valuations are high. This usually means less volatility and less upside in rallies.
How long should I stay invested in a balanced advantage fund?
There is no fixed rule, but investors generally treat BAFs as a three to five year holding or longer. Money needed within one to two years is better placed in lower-risk debt options.