 SIF
Specialised Investment Funds (SIF) Explained: The New Middle Ground Between Mutual Funds and PMS
A practical breakdown of SEBI's new SIF category minimum investment, strategies, risk, liquidity and taxation and how it compares to…
If you already have a SIP running and your income increases, you may find yourself wondering whether to increase the existing SIP or simply start another one in the same mutual fund.
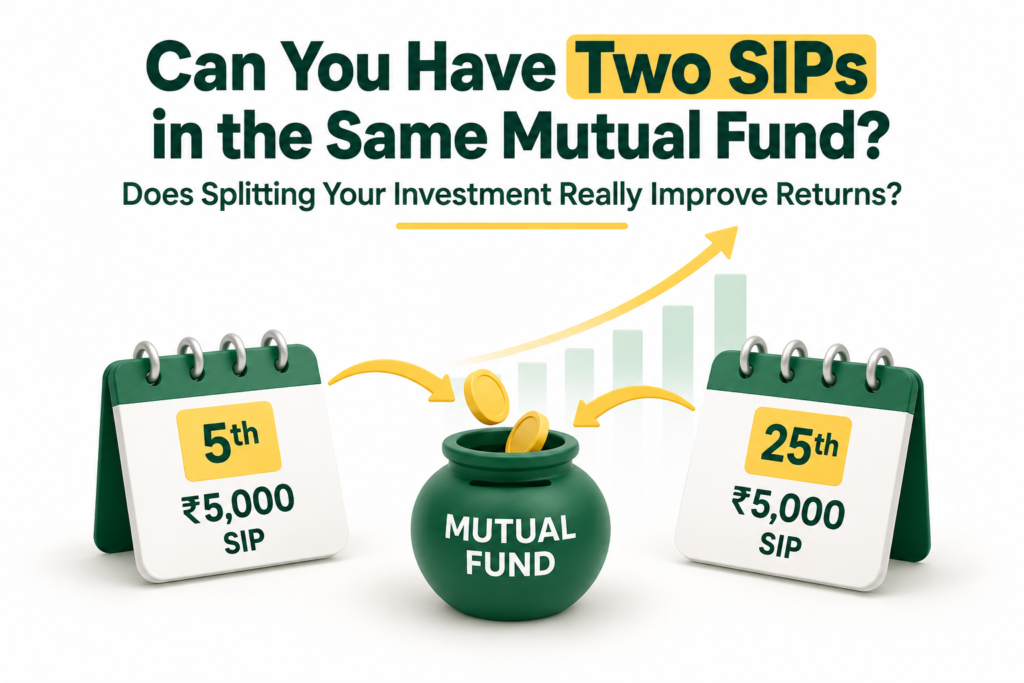
For example, you may already invest ₹5,000 every month and decide to add another ₹5,000 SIP in the same scheme, perhaps with the two investments scheduled on different dates.
Can you do that? Yes.
But the more important question is whether splitting your investment actually improves your returns.
For most investors, the answer is no. Having two SIPs in the same fund can be perfectly valid, but choosing multiple SIP dates is unlikely to make a meaningful difference to long-term wealth creation.
Yes. You can have multiple SIPs in the same mutual fund scheme, with each SIP having its own amount, debit date and frequency. So, for example, you could invest ₹5,000 on the 5th and another ₹5,000 on the 25th of every month in the same scheme.
There are practical reasons for doing this. You may have received a salary increase, your investment platform may not offer a convenient step-up facility, or you may want to keep a temporary increase in your investment separate.
The important thing is to understand that two SIPs do not create two different investment opportunities. You are still investing in the same underlying mutual fund.
This is where the idea sounds more attractive than it actually is.
Suppose you have ₹10,000 to invest every month. You can invest the entire ₹10,000 on the 5th, or split it into ₹5,000 on the 5th and ₹5,000 on the 25th.
The second approach gives you two different purchase prices. If the NAV falls between those dates, the second instalment buys more units. If the NAV rises, it buys fewer.
So yes, the purchase prices will differ. But that does not mean the strategy has a meaningful long-term advantage.
The reason is simple. A gap of a few weeks between SIP dates is small compared with the market movements that take place over several years. Your long-term outcome is driven much more by the amount you invest, the performance of the underlying investment and how long you stay invested than by whether one monthly instalment happens on the 5th or the 25th.
That is why trying to identify the “best date for SIP” is unlikely to materially change your long-term wealth.
The source analysis compared SIP investments made on the 5th, 15th and 25th of the month using the Nifty 100 and Nifty 500 across a 15-year period from 2008 to 2022, along with shorter five-year and ten-year periods. The differences between the dates were relatively small.
One example from the analysis shows this clearly:
| SIP date | Total invested | Corpus |
|---|---|---|
| 15th | ₹12,00,000 | ₹22,05,085 |
| 25th | ₹12,00,000 | ₹22,08,778 |
| Difference | ₹3,693 |
The difference was ₹3,693 on ₹12 lakh invested over ten years.
For investors who want to examine the underlying index data, NSE Indices provides historical data and information for indices including the Nifty 100 and Nifty 500. NSE Indices
The point is not that SIP dates never affect returns. They do. The point is that the difference is generally too small and inconsistent to make SIP-date selection a major investment strategy.
There are several situations where having two SIPs in the same fund is completely reasonable.
If your income has increased and your platform does not make it easy to increase the existing SIP, adding another SIP can be a practical solution.
A second SIP can also make sense when the additional investment is temporary. For example, you may want to invest an extra ₹5,000 for a defined period and then stop it without changing your original SIP.
In both cases, the second SIP is helping you manage your cash flow. It is not creating a special return advantage.
If your income is rising regularly, a step-up SIP may be a simpler way to increase your investment over time.
If you are considering two ₹5,000 SIPs purely because you believe investing on two dates will improve your returns, there is little reason to do so. If you have a practical reason for the second SIP, there is nothing wrong with maintaining it.
The better question is whether your overall investment strategy is doing what it should.
Are you investing enough? Are your mutual funds appropriate for your goals? Is your portfolio taking the right amount of risk? Are you increasing your investments as your income grows?
These decisions are likely to matter much more than whether your SIP is processed on the 5th or 25th.
For investors thinking about the bigger distinction between short-term market activity and long-term wealth creation, see our analysis on short-term trading versus long-term investing.
SIP-date optimisation can be tempting because it feels like something you can control.
But investing is not about controlling every small variable. It is about getting the important decisions right and sticking with them.
A well-structured investment plan should focus on:
| What to review | Why it matters |
|---|---|
| Monthly investment amount | Determines how much capital you put to work |
| Fund selection | Determines where your money is invested |
| Asset allocation | Determines the portfolio’s overall risk |
| Investment horizon | Gives compounding time to work |
| Annual investment increase | Helps investments keep pace with rising income |
| Investor behaviour | Prevents emotional decisions during market volatility |
This is also why a portfolio review should look beyond individual SIP registrations. A portfolio can have perfectly timed SIPs and still be poorly structured.
At SJS Finserve, the useful question is not simply whether you can create another SIP. It is whether doing so improves your overall financial plan.
Two SIPs in the same fund may be appropriate if they solve a genuine cash-flow or platform issue. But if the only reason is the belief that two different dates will produce significantly better returns, the evidence does not support making that a central investment strategy.
The bigger opportunity is usually to look at the portfolio as a whole: the amount being invested, the choice of funds, asset allocation, financial goals and the ability to remain invested through different market conditions.
That is where thoughtful wealth management can be more valuable than trying to optimise every small detail.
For most investors, the bigger questions are how much they invest, whether their portfolio is aligned with their goals and whether they can remain disciplined through different market cycles.
If you want to review whether your SIPs and mutual fund portfolio are actually aligned with your broader financial goals, SJS Finserve can help you look beyond individual transactions and assess the portfolio as a whole.
Yes. You can run multiple SIPs in the same mutual fund, with different amounts and debit dates.
Yes, the NAV and therefore the number of units purchased can differ between dates. However, the long-term difference between SIP dates is generally small based on the analysis used here.
There is no consistently superior SIP date. The historical analysis cited above found relatively small differences between the dates examined.
Not simply to improve returns. You can do it for practical reasons such as managing cash flows or working around a platform’s limitations.
If you regularly want to increase your investment as your income grows, a step-up SIP can keep the investment structure simpler. A second SIP can still be useful when there is a practical reason for keeping the additional investment separate.
For investor education and regulatory information, you can refer to SEBI’s mutual fund resources and AMFI’s official website.
SIF
A practical breakdown of SEBI's new SIF category minimum investment, strategies, risk, liquidity and taxation and how it compares to…
 Investment Strategies
A data-backed comparison of daily, weekly, and monthly SIP returns across five equity fund categories and five investment horizons. Find…
 Market Analysis
Equity mutual fund inflows rose to ₹29,329 crore in August 2026, up 19% from July, driven by record small-cap inflows…