 SIF
Specialised Investment Funds (SIF) Explained: The New Middle Ground Between Mutual Funds and PMS
A practical breakdown of SEBI's new SIF category minimum investment, strategies, risk, liquidity and taxation and how it compares to…
For young investors, retirement often feels like a problem for another decade. There are careers to build, homes to plan, experiences to enjoy, and immediate financial priorities competing for attention.
That is precisely why retirement investing is so easy to postpone.
The thought usually sounds reasonable: I will start once my income increases. I will invest more after a few promotions. I have plenty of time.
The problem is that investing does not reward intention. It rewards time.
A decade of delay can make a surprisingly large difference to the wealth you eventually accumulate, even when the monthly investment amount and expected return remain exactly the same.
Consider two friends, Aarav and Karan.
Both begin their careers with broadly similar ambitions. They want financial independence in their later years and have a retirement goal in mind. But they make different decisions when it comes to investing.
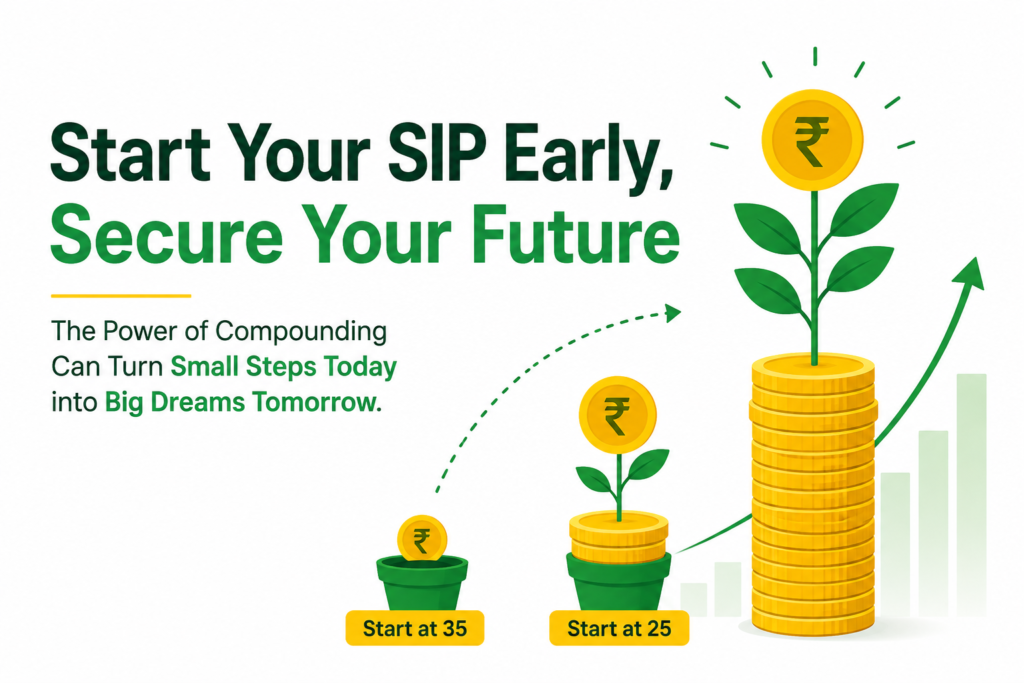
Aarav decides to start a ₹5,000 monthly SIP in equity mutual funds at age 25. His objective is simple: build a long-term investment habit and give his money as much time as possible to compound.
Karan takes a different approach. Retirement appears too distant, so he postpones investing. He spends more of his early income on lifestyle upgrades and tells himself that he will catch up once his salary grows.
At 35, Karan finally begins investing ₹5,000 every month.
From this point onward, assume both investors continue until age 60 and earn an expected annual return of 12%.
The difference is not the SIP amount. It is the 10-year head start.
| Particulars | Aarav | Karan |
|---|---|---|
| Starting age | 25 | 35 |
| Monthly SIP | ₹5,000 | ₹5,000 |
| Expected annual return | 12% | 12% |
| Investment period | 35 years | 25 years |
| Retirement age | 60 | 60 |
| Total amount invested | ₹21 Lakh | ₹15 Lakh |
| Estimated corpus at age 60 | ₹2.76 Crore | ₹85.11 Lakh |
| Total gains | ₹2.55 Crore | ₹70.11 Lakh |
Source: ET Money SIP Calculator. Figures are based on the assumptions provided above.
Aarav contributes ₹6 lakh more than Karan over the investment period. Yet the difference in their estimated retirement corpus is much larger.
Aarav ends up with an estimated ₹2.76 crore, compared with ₹85.11 lakh for Karan.
This is where compounding becomes important.
The early contributions made by Aarav do not simply remain invested. Over a longer period, the returns generated on those investments have more time to generate further returns. The effect becomes increasingly significant as the investment horizon extends.
In other words, time becomes an important part of the investment strategy.
A common response to starting late is straightforward: If I missed ten years, I can simply invest more now.
That approach can certainly help. But it does not necessarily recreate the advantage of starting earlier.
Suppose Karan doubles his SIP at age 35, investing ₹10,000 every month instead of ₹5,000.
The comparison changes:
| Particulars | Aarav | Karan |
|---|---|---|
| Starting age | 25 | 35 |
| Monthly SIP | ₹5,000 | ₹10,000 |
| Investment period | 35 years | 25 years |
| Total amount invested | ₹21 Lakh | ₹30 Lakh |
| Estimated corpus at age 60 | ₹2.76 Crore | ₹1.70 Crore |
Source: ET Money SIP Calculator. Figures are based on the assumptions provided above.
Karan now invests ₹9 lakh more than Aarav in total. Yet the estimated corpus still falls significantly short of Aarav’s ₹2.76 crore.
The lesson is not that investing a larger amount is ineffective. Quite the opposite. Increasing the SIP can be an important way to accelerate wealth creation.
The lesson is that money invested earlier has more time to compound.
For an investor who starts late, the solution is often a combination of a higher investment amount, disciplined investing, and realistic expectations about the time required to reach the desired corpus.
Under the assumptions in this example, Karan would need to invest approximately ₹15,000 per month over 25 years to target a corpus comparable to Aarav’s ₹2.76 crore.
The cost of waiting is not always visible in the first few years.
That is what makes delaying investment particularly easy.
If you postpone a ₹5,000 SIP today, you may simply feel that you have saved ₹5,000 this month. Nothing appears to have gone wrong.
But the opportunity cost extends beyond that single contribution. You have also removed that money’s potential to remain invested and compound over several decades.
This creates an important distinction between saving money and giving money time to grow.
A young investor does not necessarily need a very large starting amount. What can matter more is establishing the habit early and increasing the contribution as income rises.
For example, someone beginning with a manageable SIP can gradually increase it as their salary, business income, or financial capacity improves. This approach can make long-term investing more sustainable than waiting for the perfect income level before starting.
The biggest takeaway from the example is not that every investor should immediately invest a particular amount or expect a particular return.
The 12% return used here is an assumption for illustration, not a guaranteed investment outcome. Actual mutual fund returns can be higher or lower, and market-linked investments involve risk.
The more durable lesson is about investment behaviour.
Three things deserve attention:
Start with a sustainable amount.
An SIP should fit within your cash flow rather than create financial stress. Consistency over a long period is more useful than choosing an amount you cannot maintain.
Increase investments as income grows.
Starting early does not mean remaining stuck at the same SIP amount. Periodic increases can help your investments keep pace with rising income and long-term goals.
Do not confuse market volatility with investment failure.
Long-term investing inevitably involves periods of market declines. A retirement strategy should be designed around an appropriate time horizon, asset allocation, risk tolerance, and financial objectives rather than short-term market movements alone.
Investors often spend considerable time trying to identify the right mutual fund, the right market level, or the right time to begin.
Those decisions can matter, but for a young investor with a multi-decade horizon, another question deserves equal attention:
Have I started at all?
The difference between starting at 25 and starting at 35 can be substantial even when the monthly SIP is identical.
That does not mean someone who starts at 35, 40, or later has missed their opportunity. It simply means the strategy may need to change. A longer investment period provides one advantage. When that advantage is no longer available, investors may need to compensate through higher contributions, longer working periods, increased savings, or a combination of these factors.
The important point is to avoid turning a delayed start into another reason for further delay.
A SIP calculator can demonstrate the mathematics of compounding, but retirement planning is bigger than a single calculation.
Your retirement corpus depends on factors such as your desired lifestyle, current savings, income growth, inflation, investment horizon, asset allocation, and the amount you can realistically invest.
That is why the right SIP is not necessarily the largest SIP you can afford today. It is the amount that works within a broader financial plan and can be increased as your circumstances change.
At SJS Finserve, we believe investment decisions should be connected to actual financial goals rather than made in isolation. Whether you are just starting your investment journey or trying to assess whether your existing retirement strategy is on track, a structured review can help you understand the gap between where you are today and where you want to be.
1. Why is starting a SIP early important?
Starting early gives your investments more time to benefit from compounding, potentially helping you build a larger corpus over the long term.
2. Can I catch up if I start investing late?
Yes. Starting late does not make wealth creation impossible, but you may need to invest a higher amount or extend your investment horizon.
3. Is a 12% SIP return guaranteed?
No. The 12% return used in the example is an assumed rate for illustration. Mutual fund returns are market-linked and not guaranteed.
4. Should I increase my SIP as my income grows?
Increasing your SIP periodically can help you invest more as your income increases and may support your long-term financial goals.
5. How much should I invest through SIP for retirement?
The right SIP depends on your retirement goal, age, income, existing investments, time horizon, and expected expenses. A professional financial assessment can help determine an appropriate amount.
SIF
A practical breakdown of SEBI's new SIF category minimum investment, strategies, risk, liquidity and taxation and how it compares to…
 Investment Strategies
A data-backed comparison of daily, weekly, and monthly SIP returns across five equity fund categories and five investment horizons. Find…
 Market Analysis
Equity mutual fund inflows rose to ₹29,329 crore in August 2026, up 19% from July, driven by record small-cap inflows…